Why the Economy Feels Worse Than the Data Says
Consumer sentiment hit 47.8, the second-lowest on record, while jobs data stayed solid. Here is what explains the gap, and which signal to actually trust.
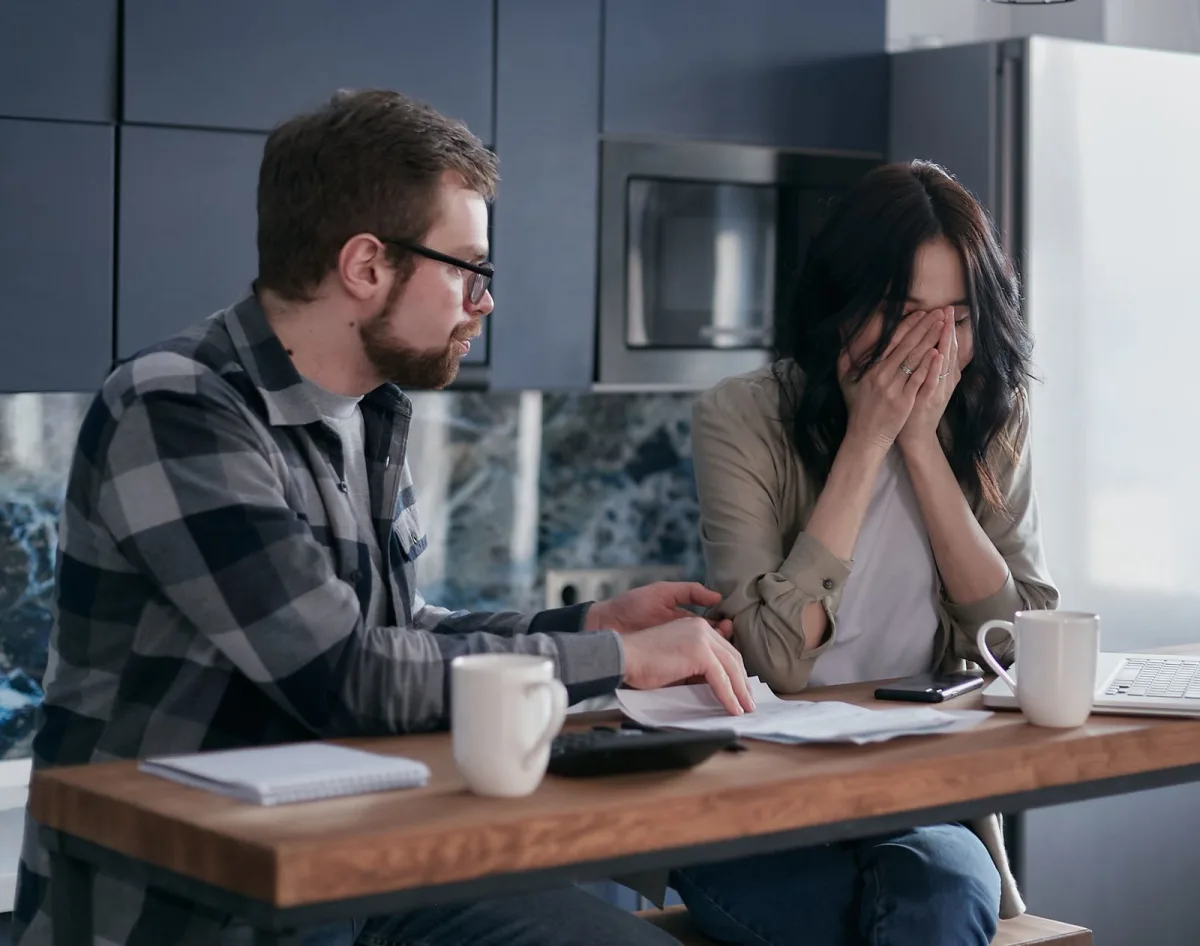
Table of contents
The jobs report came in strong. Unemployment claims fell. Employers added 162,000 positions in August, the most since March.
And in the same month, consumer sentiment fell to 47.8, the second-lowest reading ever recorded.
Those two facts are both true, published days apart, describing the same economy. One says things are fine. The other says people feel worse than they did in 2008.
This gap is not confusion or people being badly informed. There is a specific, measurable reason for it, and understanding it tells you more about your own finances than either number does alone.
Key Takeaways
- Consumer sentiment fell to 47.8 in early September, down from 51.7, against expectations of 51.0.
- That is the second-lowest reading on record, and it sits below the index level at the start of all six recessions since the survey began.
- Employers added 162,000 jobs in August, the strongest month since March, and jobless claims fell.
- Year-ahead inflation expectations jumped from 4.0% to 4.6%, the highest since June.
- Sentiment tracks prices and direction, while jobs data tracks employment, which is why the two can diverge for long stretches.
The Two Numbers Side by Side
Start with what each one actually measured.
The sentiment reading. The University of Michigan Surveys of Consumers index fell to 47.8 in its early September print, down 3.9 points from August's 51.7, and well under the 51.0 economists expected. It was the second consecutive monthly decline. The only lower reading on record came earlier this year.
One comparison makes the scale clear: 47.8 is below the index level recorded at the start of all six recessions since the survey began.
The labour data. Employers added 162,000 jobs in August, the best month since March and above what most analysts forecast. New unemployment claims unexpectedly fell. By the standard measures, the job market is on solid footing.
So one instrument reads recession and the other reads expansion. Both are accurate. They are measuring different things.
What Sentiment Is Actually Tracking
The survey asks people how they feel about their finances, business conditions, and buying conditions, now and looking ahead. In practice, answers track two things far more than employment.
Prices, especially visible ones. Gasoline rose more than 27% over the year. Energy rose 16.3%. These are the prices people see repeatedly, posted on signs, with no way to avoid noticing. A stable paycheque does not offset the experience of paying more every week for something you must buy.
Direction rather than level. Having a job is a level. Watching prices rise faster than your raise is a direction. Humans weight direction heavily, which is why sentiment can fall while employment holds.
The survey itself shows this. Year-ahead inflation expectations jumped from 4.0% to 4.6%, the highest since June. Respondents cited fuel prices and trade tensions specifically. They are not reporting that they lost a job. They are reporting that they expect things to cost more.
This is the same distortion we worked through in why your personal inflation rate is not the headline number. Headline inflation was 3.4%, but the categories people notice most rose far faster.
Why Both Can Be Right
Work through a household to see how the two coexist.
Take a family earning $80,000 who kept their jobs and received a 3% raise, so $2,400 more for the year.
Now their costs:
- Spending 12% of income on fuel and energy, roughly $9,600, rising 16.3%, adds $1,565
- Spending 30% on housing, $24,000, rising 3.0%, adds $720
- Spending 15% on food, $12,000, rising 2.7%, adds $324
Those three categories alone consume $2,609 of a $2,400 raise.
This household is employed, got a raise, and appears in the labour data as a success. They are also $209 worse off before accounting for anything else they buy. Asked how the economy is doing, they will not say it is fine.
That is the entire gap in one worked example. The jobs number counts whether they work. The sentiment number captures whether the arithmetic works.
Does Low Sentiment Predict a Recession
This is where it gets genuinely uncertain, and worth being careful.
The case for concern is real. A reading below the level seen at the start of all six previous recessions is not nothing. Consumer spending drives most economic activity, and people who feel poor eventually spend like it.
The case against is also strong. Sentiment has become a poor predictor over the last several years, repeatedly signalling downturns that did not arrive while employment stayed firm. The relationship that made it useful appears to have weakened.
The honest position is that sentiment now measures how expensive life feels rather than forecasting what the economy will do. That makes it a good description of household reality and an unreliable crystal ball.
For the full picture of what does signal a downturn, our look at whether a global recession is coming covers the indicators with better track records.
What to Actually Do With This
Three practical responses, none of which involve predicting the economy.
Measure your own position instead of the national one. Take your raise, subtract what your three biggest categories actually rose, and see what is left. That single calculation tells you more than any headline, and it is the number to bring to a salary conversation.
Treat inflation expectations as a planning input. Households expect 4.6% inflation over the year ahead. Expectations partly drive outcomes, because people who expect higher prices accept them faster. Budget against something closer to that figure than to the reported 3.4%.
Do not make big decisions on sentiment alone. Selling investments because confidence is low has been a reliably poor move during this period, since the sentiment readings kept being wrong about what came next. If you hold index funds, the more useful thing to check is how concentrated your fund actually is, which is a measurable risk rather than a mood.
Frequently Asked Questions
What is the current consumer sentiment reading?
The University of Michigan index fell to 47.8 in its early September reading, down from 51.7 in August and below the 51.0 expected. It was the second consecutive monthly decline and the second-lowest level in the survey's history.
Why does the economy feel bad when jobs numbers are good?
The two measure different things. Jobs data tracks whether people are employed, while sentiment tracks prices and direction. With gasoline up more than 27% and energy up 16.3%, a household can keep its job, receive a raise, and still end the year worse off once those increases are absorbed.
Does low consumer sentiment mean a recession is coming?
Not reliably. The current reading sits below the level recorded at the start of all six recessions since the survey began, which is concerning. But sentiment has repeatedly signalled downturns in recent years that did not arrive, so its predictive value has weakened considerably.
What are consumers expecting inflation to be?
Year-ahead inflation expectations rose from 4.0% to 4.6%, the highest since June. That is well above the 3.4% currently reported, and respondents attributed the increase mainly to fuel prices and trade tensions.
How many jobs did the economy add recently?
Employers added 162,000 jobs in August, the strongest month since March and above most analyst forecasts. New unemployment benefit claims also fell unexpectedly, indicating the labour market remains on solid footing.
The Bottom Line
Both numbers are honest. One counts jobs and the other counts how it feels to pay for things, and right now those point in opposite directions.
The worked example explains why: a household can receive a 3% raise and still lose ground when the categories they cannot avoid rise faster than that.
Run that calculation on your own numbers rather than arguing with the headlines. Whichever national figure you believe, the one that determines your decisions is the gap between your raise and your actual costs.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult with a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.
Written by
Quick Trend Insights Editorial Team
Our editors track the latest in technology, business, finance, and culture, turning fast-moving news into clear, reliable insight you can act on.