Why Your Budget Keeps Failing (It's Not Discipline)
Most budgets fail for behavioral reasons, not willpower. Here's what actually derails budgeting and the practical fixes that hold up over the long term.
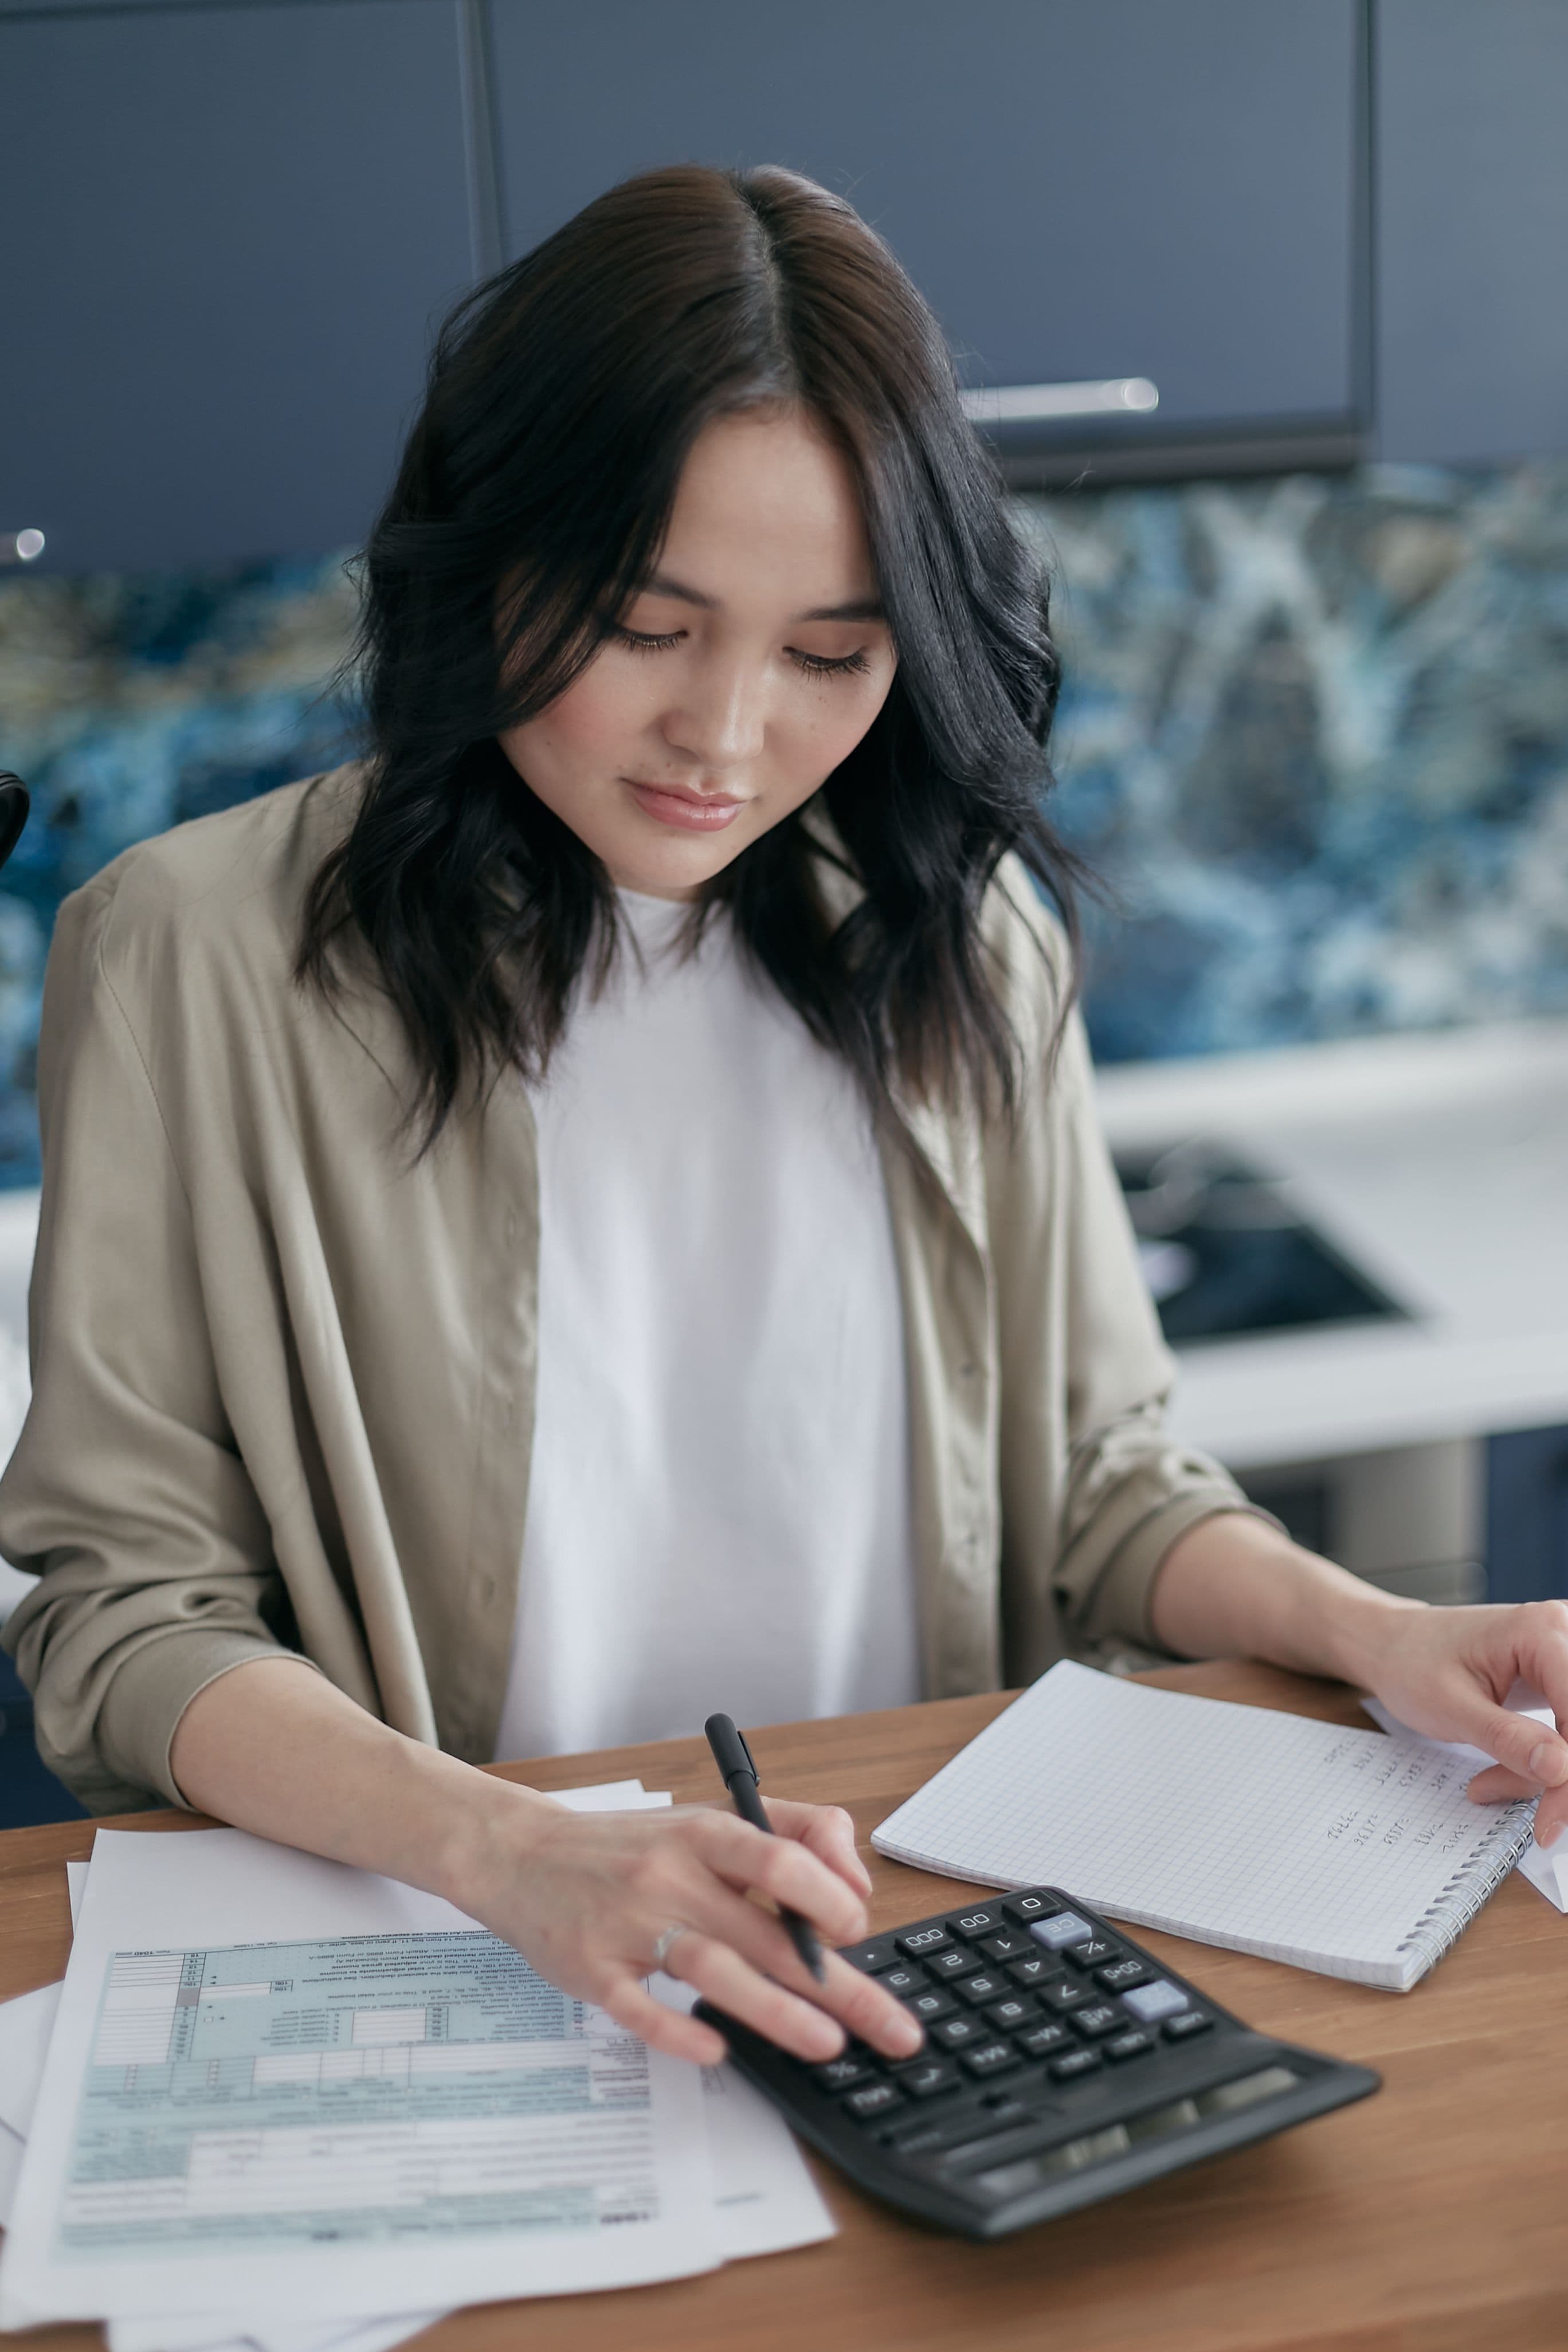
Table of contents
You have downloaded three budgeting apps this year. You have color-coded a spreadsheet, set spending caps, and promised yourself that this time the budget will stick. Two weeks in, a card gets swiped on something not in the plan, the whole system feels broken, and you quietly stop checking it.
Here's the uncomfortable part: none of that happened because you lack discipline. Behavioral economists have spent decades studying exactly why budgets collapse, and willpower barely shows up in the research. The real culprits are predictable, well-documented mental shortcuts that push everyone — including people who are otherwise careful with money — toward the same failure points.
Once you can see the trap, you can design around it instead of fighting it. This piece breaks down the specific behavioral patterns that sink budgets, and the structural fixes that actually hold up when life gets messy.
Key Takeaways
- Budgets fail because of predictable cognitive biases — present bias, mental accounting, and all-or-nothing thinking — not weak willpower.
- Present bias makes future goals feel abstract, so your brain consistently favors today's spending over tomorrow's savings.
- Automation and separate accounts remove the moment-to-moment decisions that biases exploit, which is why they outperform manual tracking long term.
- A hybrid approach — automated transfers plus light manual tracking — tends to beat either pure automation or pure willpower-based budgeting.
The Budgeting Myth: Why Willpower Isn't the Real Problem
Most budgeting advice assumes failure is a motivation problem: try harder, want it more, be more disciplined. Behavioral finance research tells a different story. Nobel laureate Richard Thaler and other researchers in the field have shown that people consistently make choices that contradict their own stated financial goals — not because they're careless, but because the human brain is wired with systematic decision-making shortcuts that override good intentions in the moment.
Think of it this way: a budget is a plan made by your "future-focused" self, but every purchase decision gets made by your "in-the-moment" self. Those two selves want different things, and the in-the-moment self usually wins because it's the one holding the card. This is why the same smart, motivated person can build a perfect spreadsheet on Sunday and blow through it by Wednesday.
Recognizing this reframes the whole problem. If budgets fail for structural, psychological reasons rather than character flaws, then the fix isn't more guilt or more tracking apps — it's designing a system that doesn't rely on willpower in the first place. That's the approach the rest of this article builds toward.
The Behavioral Traps That Sink Budgets
Three specific biases show up again and again in budgeting failures, and each one has a name in behavioral economics.
Present bias is the tendency to overvalue immediate rewards and undervalue future ones, even when you know the math doesn't favor the immediate choice. It's why skipping a night out to hit a savings goal feels harder in the moment than it looked on paper last week. Present bias is a well-documented driver of under-saving: people consistently plan to save "starting next month," and next month never quite arrives.
Mental accounting, a concept popularized by Thaler, describes how people treat money differently depending on which mental "bucket" it sits in, even though a dollar is a dollar. A tax refund gets spent freely because it feels like "bonus money," while the same amount in a checking account would trigger caution. This is also why people carry high-interest credit card debt while keeping a low-interest savings account untouched — the accounts feel separate even though the math says they shouldn't be.
All-or-nothing thinking is what turns one overspent category into a fully abandoned budget. A single unplanned purchase feels like proof the system failed, so the natural response is to scrap it rather than adjust one number and move on. None of these are moral failures — they're default settings in how people process money, and a budget that ignores them is set up to lose.
A Budget Framework Built Around How People Actually Behave
Instead of designing a budget for an idealized, perfectly rational person, build one for how people genuinely behave. That means using structure to do the work that willpower keeps failing to do.
Start with separate accounts for separate purposes — bills, discretionary spending, and savings in physically different places rather than one account you mentally divide with a spreadsheet. This works with mental accounting instead of against it: if "fun money" only exists in a specific account with a specific balance, overspending becomes visible immediately instead of getting lost in a shared pool.
Next, build in automation at the moment money arrives, not after bills are paid. When a transfer to savings happens on payday, before you ever see the money in your spending account, present bias never gets a chance to argue against it. This is the same principle behind the "Save More Tomorrow" program, where employees committed in advance to save a larger share of future raises — a real-world test that pushed retirement savings rates from around 3.5% to over 13% for participants over several years, according to research on automatic saving plans.
Finally, add friction to the spending you want less of — remove saved cards from shopping apps, unsubscribe from retail emails, or require a 24-hour wait before non-essential purchases above a set amount.
Small Structural Changes That Beat Willpower
You don't need a total system overhaul to see results. A handful of specific, low-effort changes consistently outperform sheer determination.
Automatic transfers on payday, even a modest amount, compound into real savings without a single daily decision. Something as simple as a $50 automatic transfer to a separate high-yield savings account, timed to the day you get paid, removes the temptation entirely because the money is gone before you can spend it.
Spending caps with alerts on categories like dining out or subscriptions catch overspending while there's still time to course-correct, rather than at month's end when the damage is done. Most banking apps now offer this for free, and it turns a vague intention into a concrete guardrail.
Visual tracking — a simple progress bar toward a savings goal, or a red/yellow/green indicator for category spending — taps into how people actually process information. Numbers on a spreadsheet are abstract; a shrinking bar or a color change is immediate and intuitive, which makes it far more likely to change behavior in the moment.
None of these tactics require more discipline than you have right now. They simply move the decision point earlier, to a moment when your future-focused self is in charge, instead of leaving it for the moment your in-the-moment self is holding the wallet. If you're also working on building additional income streams, the same automation principle applies — route new income into savings or investing by default before it ever hits your everyday spending account.
When to Automate vs. When to Manually Track — and Why Hybrid Usually Wins
Full automation is powerful, but it isn't a complete solution on its own. If every dollar is on autopilot, you can lose the awareness that helps you catch a subscription you forgot about or notice your grocery spending has crept up over several months.
Pure manual tracking has the opposite problem: it depends entirely on consistency, and consistency is exactly what present bias and all-or-nothing thinking erode over time. Most people who try to log every transaction by hand abandon it within a few months, not because the method is wrong, but because it demands a level of sustained attention that few daily habits survive.
The hybrid model tends to win because it plays to the strengths of both. Automate the decisions that don't need daily judgment — savings transfers, bill payments, retirement contributions — so they happen without relying on motivation. Then reserve manual attention for the smaller number of categories where judgment actually matters, like discretionary spending, using a quick weekly check-in rather than daily logging.
This lighter-touch review also fits naturally alongside longer-term financial planning. If you're still building your investing foundation, the same hybrid logic applies there too — automate contributions, then check in periodically rather than reacting to every market move.
Frequently Asked Questions
Why do budgets fail even when I stick to them for a few weeks?
Most budgets fail because they rely on constant willpower rather than structure. Present bias and all-or-nothing thinking tend to surface a few weeks in, once the initial motivation fades and the first unplanned expense hits.
What is mental accounting and how does it affect my budget?
Mental accounting is the tendency to treat money differently based on where it came from or what "bucket" it's mentally assigned to, even though it's all the same money. It affects budgets by making certain funds — like a bonus or refund — feel safer to spend than money in a checking account.
Is it better to automate my budget or track spending manually?
A hybrid approach generally works best: automate savings transfers and bill payments so they don't depend on daily willpower, then use light manual tracking for discretionary categories where judgment matters most.
How much should I automatically transfer to savings each payday?
There's no universal number, but starting with a modest, sustainable amount — even 5-10% of your paycheck — and increasing it gradually tends to stick better than an aggressive amount you're likely to reverse after a few months.
Budgets don't fail because people are careless with money — they fail because most budgets are designed for a perfectly rational person who doesn't actually exist. Once you build a system around automation, separate accounts, and friction where you need it, the biases that used to derail you stop mattering as much, because the decisions happen before your in-the-moment self ever gets a vote.
The next time a budget falls apart, resist the urge to blame discipline. Look instead at where the system asked you to make a moment-to-moment decision it should have made for you in advance — and fix that one structural gap.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult with a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.
Written by
Quick Trend Insights Editorial Team
Our editors track the latest in technology, business, finance, and culture, turning fast-moving news into clear, reliable insight you can act on.
Related Articles
View all