
MSME Loans: Why the RBI Wants Banks to Lend Small
MSME loans are in focus after the RBI Governor urged banks to lend small. See the credit gap, the ₹20 lakh collateral-free rule and what changes for you.
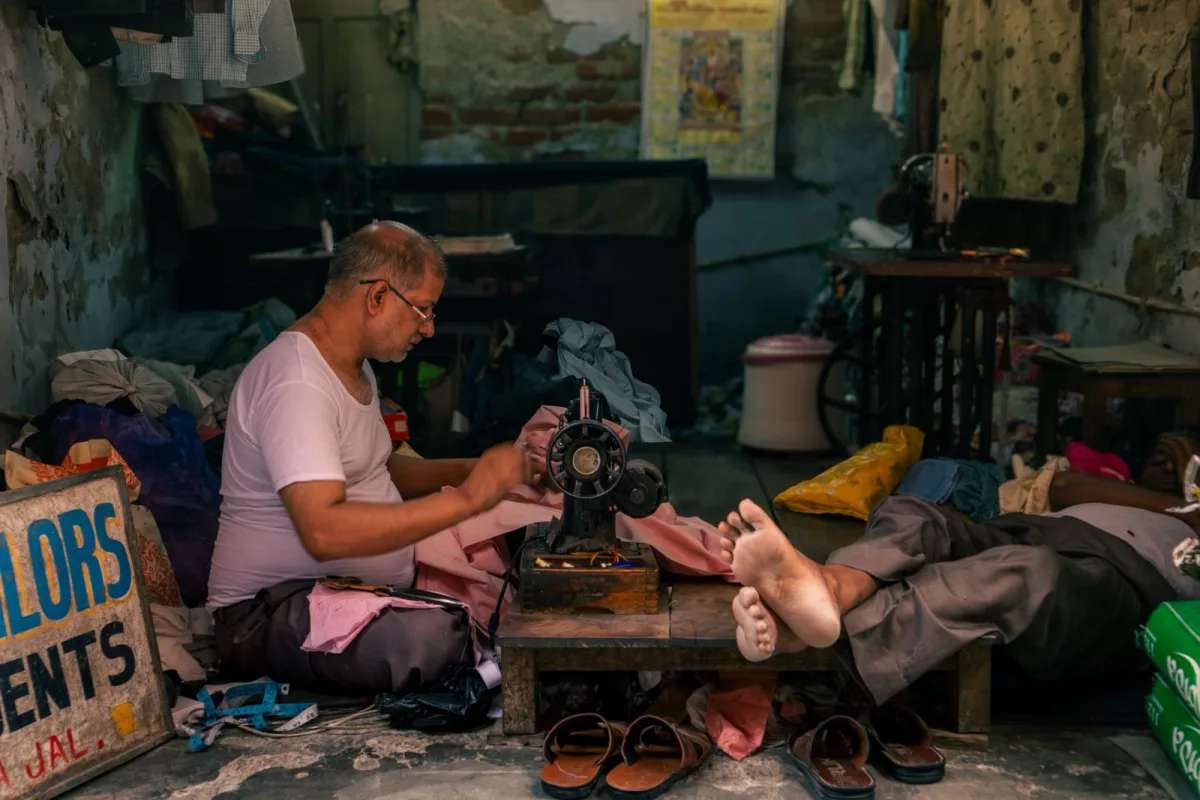
Table of contents
You run a small fabrication unit outside Pune. A buyer offers you an order twice your usual size, but you need ₹15 lakh for steel up front. The bank asks for property papers you do not have, so you borrow from a local lender at a rate that eats most of the profit.
That gap between what small firms need and what banks hand over is why MSME loans were at the center of a speech by Reserve Bank of India Governor Sanjay Malhotra on November 21. Speaking at a financial inclusion camp in Waksai village in Pune district, he made what he called a "special appeal" to bankers: a ₹1,000 crore loan to one large company helps one business, but the same money spread across small enterprises could have "at least a hundred times greater" impact, and a thousand times more across micro borrowers, PTI reported.
Here is why MSME credit matters to India's economy, how big the shortfall is, the tools the RBI and the government use to close it, and what changes for you if you are applying for a loan.
Why MSME Loans Matter to India's Economy
Micro, small and medium enterprises are not a niche. In a June speech, Malhotra cited the Economic Survey: MSMEs contribute 31% of GDP, about 35% of manufacturing output, and close to half of India's merchandise exports. Udyam portal data he quoted showed the sector sustains livelihoods for more than 32 crore people.
Credit decides whether those firms grow or stall. A tailor who can buy a second machine hires a helper. A food processor who gets working capital can accept a supermarket order with 60-day payment terms instead of turning it down. Each loan feeds wages, purchases from suppliers and tax receipts, which is the chain Malhotra had in mind with his hundred-times comparison.
Why the "100 times" claim holds up as a direction, not a formula
Malhotra's multiplier is an illustration, not a measured result, and he did not cite a study behind it. The logic is about breadth. Divide ₹1,000 crore into collateral-free loans of ₹20 lakh and you get 5,000 separate businesses, each with its own workers and suppliers. Lent to one conglomerate, the same sum might fund a single plant that would likely have found financing elsewhere.
Small loans also cost banks more to process per rupee, and they carry more perceived risk. That is why the RBI is pushing rather than assuming banks will get there on their own.
How Big Is the MSME Credit Gap?
Bank lending to the sector has grown fast. Scheduled commercial bank credit to MSMEs stood at ₹36.79 lakh crore on December 31, 2025, Malhotra said in June, growing about 15% a year over five years against 13.7% for bank credit overall.
Growth is not the same as enough. A May 2025 report by the Small Industries Development Bank of India (SIDBI) and Crisil, still SIDBI's latest estimate, found:
- Addressable debt demand of about ₹64 lakh crore against formal supply of about ₹34 lakh crore.
- An unmet gap of about ₹30 lakh crore, roughly 24% of total finance demand.
- A gap of about 35% for women-owned firms, against about 20% for male-owned ones.
Access is thin at the base. The MSME Pulse report from SIDBI and TransUnion CIBIL, published in July, found that only about 3.6 crore of 8.7 crore registered MSMEs, or 41%, had ever taken formal credit. The rest rely on savings, family, trade credit or moneylenders.
The Tools RBI and the Government Use
There is no single scheme. Four levers work together, and each tackles a different reason banks hold back.
1. Priority sector lending targets
Under the RBI's priority sector lending directions, domestic commercial banks must direct 40% of adjusted net bank credit to priority sectors such as agriculture, MSMEs and weaker sections. Within that, 7.5% is earmarked for micro enterprises. A bank that falls short has to put the shortfall into lower-yielding government funds, so the target has a cost attached.
The weak spot is that a quota can be met without enthusiasm. In June, Malhotra asked lenders to treat MSMEs as long-term partners rather than a regulatory obligation, Business Today reported.
2. Credit guarantees through CGTMSE
The Credit Guarantee Fund Trust for Micro and Small Enterprises promises to repay a lender a large share of a loan if the borrower defaults. Its ceiling rose from ₹5 crore to ₹10 crore per borrower from April 2025, and the annual guarantee fee starts at 0.37%, according to CGTMSE.
The RBI adds a capital incentive. It assigns a zero risk weight to the guaranteed portion of these loans, so a bank does not have to set aside capital against that slice. For a bank, that turns a risky small loan into a far cheaper one to hold.
3. Collateral-free lending rules
The RBI's February amendment to its MSME lending directions doubled the collateral-free limit for micro and small enterprises from ₹10 lakh to ₹20 lakh, for loans sanctioned or renewed from April 1. Malhotra said in June that banks may go up to ₹25 lakh for firms with a consistent track record. The RBI also clarified that voluntarily pledging gold or silver within that limit does not breach the rule.
4. Digital rails that replace paperwork
Many micro firms have no audited accounts but plenty of digital payment history. The Account Aggregator framework lets you share bank statements and GST data with a lender in minutes, with your consent. Malhotra said it enabled about ₹3.5 lakh crore of lending in 2025-26, and he has urged banks to use it along with the Unified Lending Interface and TReDS, the platform that lets firms sell unpaid invoices for early cash.
What Changes When You Apply for an MSME Loan
Start with whether you count. Since April 2025, a micro enterprise is one with up to ₹2.5 crore invested in plant and machinery and turnover up to ₹10 crore, under a government notification. Small enterprises go up to ₹25 crore and ₹100 crore. Register on the Udyam portal, because banks use that certificate to classify your loan as priority sector.
Then use the rules in your favor:
- Below ₹20 lakh, refuse collateral demands. Banks may not take collateral on these loans. If a branch insists on property papers, ask for the refusal in writing and escalate.
- Ask about CGTMSE cover. It can make a branch say yes to a larger loan, but ask whether the guarantee fee will be passed on to you.
- Share your digital trail. Consent to Account Aggregator access so the lender sees GST filings and UPI receipts, not just a thin balance sheet.
The same tension shows up abroad. In the US, community banks are moving the other way, as our piece on why banks want more collateral for small business loans explains. India's rules now go further than most in barring it for the smallest borrowers.
A worked example: what a ₹20 lakh loan really costs
Say you borrow ₹20 lakh, collateral-free, over five years. Assume an interest rate of 11% a year, though your bank's actual rate depends on your credit profile and the benchmark it uses.
- Monthly EMI: about ₹43,485
- Total repaid over 60 months: about ₹26.09 lakh
- Total interest: about ₹6.09 lakh
At 12%, the EMI rises to about ₹44,489 and interest to about ₹6.69 lakh. One percentage point costs you roughly ₹60,000 over the loan. Plug your own quote into a loan EMI calculator before you sign, and compare it with what an informal lender charges you today. If your new order earns more each month than the EMI, the loan pays for itself.
Frequently Asked Questions
What is the collateral-free loan limit for MSMEs?
Banks cannot ask for collateral on loans to micro and small enterprises up to ₹20 lakh, for loans sanctioned or renewed from April 1. The RBI raised the limit from ₹10 lakh in a February amendment.
What did the RBI Governor say about MSME lending?
On November 21, Sanjay Malhotra urged banks to lend more to small and micro firms. He said ₹1,000 crore lent to small enterprises could have at least 100 times the impact of one large loan, and 1,000 times across micro borrowers.
What is the MSME credit gap in India?
SIDBI's latest estimate puts the addressable gap at about ₹30 lakh crore, roughly 24% of total finance demand. The gap is wider for women-owned and services firms.
How does the CGTMSE scheme help small businesses get loans?
CGTMSE guarantees a share of the loan to the lender, up to ₹10 crore per borrower, so the bank recovers part of its money if you default. The RBI also lets banks hold no capital against the guaranteed part.
Is Udyam registration required for an MSME loan?
It is not required for every business loan, but banks use the Udyam certificate to classify your loan as MSME priority sector lending, which is what gives you access to these protections and schemes.
Small Loans, Big Multiplier
The Governor's speech did not change any rule. What it did was put the RBI's weight behind rules that already exist: a 7.5% micro enterprise target, a ₹20 lakh collateral-free limit, guarantee cover and digital data that can stand in for property papers. Banks will move at their own pace. You can move faster by knowing what they are allowed to ask for, and what they are not.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult with a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.
Written by
Marcus Vance
Business & Money
Writes on business and personal finance for Quick Trend Insights, translating markets, rates, and company strategy into what it costs or saves a household.
Related Articles
View all
France's Economy Is Stalling: What It Means for You
France's economy shrank 0.1% as exports fell and energy pushed inflation to 3.4%, while the ECB keeps raising rates. Here is what that means for your money.
China Consumer Spending Stalls: Why It Reaches You
China consumer spending grew just 0.4% in October while exports rose 35%. Here is why Chinese shoppers stopped buying and how it reaches your prices and funds.
Underemployment Rate Rose While Unemployment Fell
The underemployment rate rose to 7.9% as unemployment fell to 4.1%. See why hours cuts drove the gap, what a lost shift costs you, and what to watch next.