
Yen Intervention: Why 160 Per Dollar Is Japan's Line
Yen intervention explained: why Japan defends 160 per dollar, what its record ¥27 trillion in yen buying achieved, and the rate gap that keeps the yen weak.
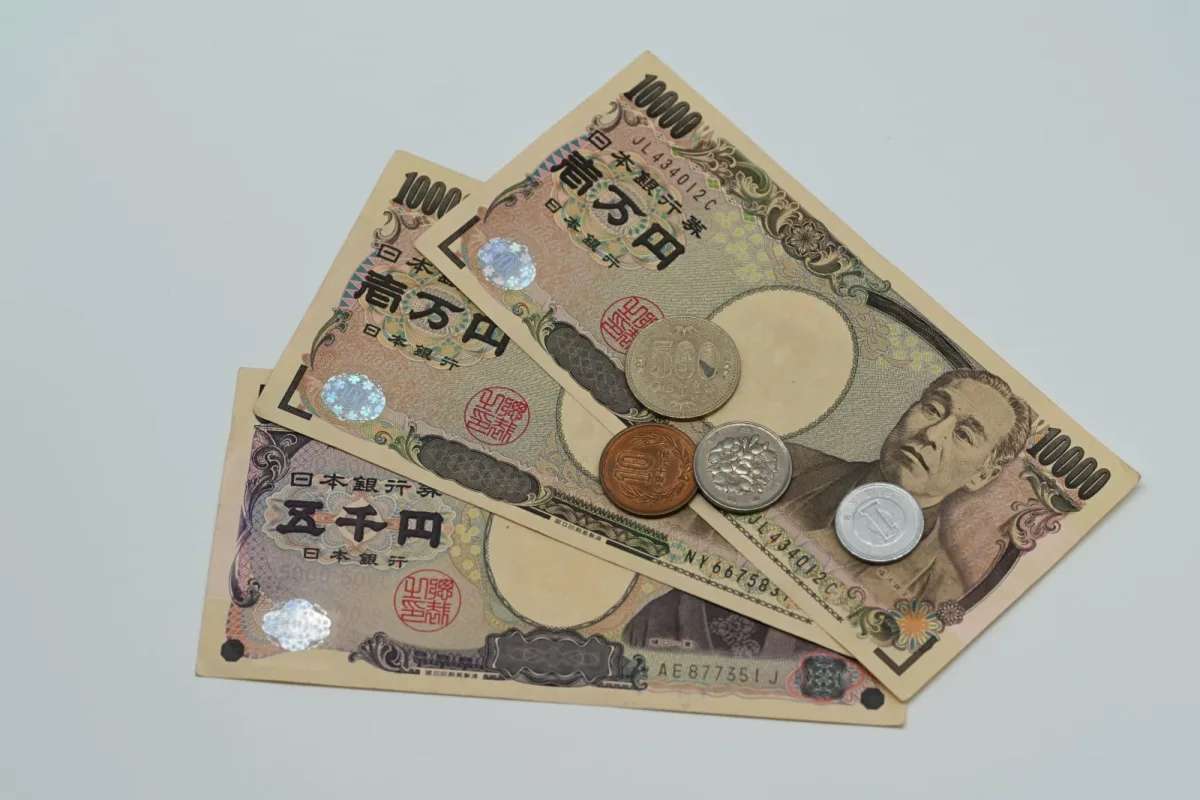
Table of contents
You open a currency app on November 13 and see one dollar buying 160 yen. A week later it buys about 158.5. Nothing in Japan's economy changed that much in seven days. What changed was the threat of yen intervention, and the market's memory of what happened the last two times the dollar crossed 160.
If you hold a Japan fund, plan a Tokyo trip, or own US stocks that wobble when global money shifts, this matters to you. Japan has spent more than ¥27 trillion defending its currency since late April. Yet the yen sits roughly where it started. This post explains why 160 has become the line, how an intervention actually works, and what would have to change for the yen to stop drifting back.
Why the Yen Keeps Testing 160 Per Dollar
Currencies follow money, and money follows yield. On November 19 the US 2-year Treasury yielded about 4.83% and the 10-year about 5.09%, according to market data reported by investingLive. Japan's 2-year bond yielded about 1.82% and its 10-year about 2.78% on November 20, per Trading Economics.
That leaves a gap of roughly 3 percentage points at the short end and 2.3 points at the long end. Every global investor choosing between the two is paid more to hold dollars. As long as that is true, the default flow runs out of yen.
The gap is not closing quickly. The Bank of Japan has raised its policy rate twice this year, in June and September, to 1.25%. Over the same stretch, the Federal Reserve turned toward hikes of its own. Saxo Bank's November 19 note said the Fed's October minutes showed nearly all officials expected further increases would likely be needed. Both central banks are tightening, so the spread between them barely moves.
Why 160 and not some other number
Officials never name a trigger level. Finance Minister Satsuki Katayama frames the concern as speed: on November 13 she said she was seeing "one-sided and rapid moves in currency markets."
The market has drawn its own line from experience. Tokyo intervened in late April after the dollar rose above 160, and again in late July after it climbed close to 164. So 160 works as a line because both interventions this year happened just above it, not because of any rule.
How Yen Intervention Actually Works
The Ministry of Finance decides. The Bank of Japan executes. The mechanics are simpler than most people expect:
- The ministry orders a sale of dollars from Japan's foreign reserves, which are held mostly in US Treasuries and deposits.
- The Bank of Japan sells those dollars in the currency market and buys yen with the proceeds, usually in large blocks during thin trading hours for maximum effect.
- The yen jumps as a wave of buying hits a market where many traders are positioned the other way and rush to cover.
- The ministry stays silent for weeks. It confirms the totals only in monthly data, and the daily breakdown only in a quarterly release.
Before any of that, officials climb a verbal ladder. On November 12, top currency diplomat Atsushi Mimura said the moves of the last few days had been "too rapid" and that it was "still too early to forget the memory of this summer," Jiji Press reported. The dollar fell from near 160 to about 159.50 within hours of his remarks. Words alone moved the market half a yen.
The US joined in this time
The July operation was different in one big way. The New York Fed disclosed that the US Treasury bought yen alongside Japan in July. It was the first US yen-buying intervention since 1998, and Jiji Press described the July 31 action as the first concerted intervention by the two countries in about 28 years.
That matters for the next round. Katayama said on November 13 that Japan would coordinate with the US Treasury. A joint move signals that Washington also wants a stronger yen, which makes betting against it riskier.
What This Year's Interventions Cost
Here is the record, all from Ministry of Finance disclosures as reported by Dow Jones, Jiji Press and The Nation:
- April 28 to May 27: ¥11.73 trillion, then a record for a single month. The largest day, April 30, was ¥6.28 trillion.
- July 30: ¥7.98 trillion, about $50.4 billion, the largest single day on record.
- July 30, July 31 and August 3 combined: about ¥15.4 trillion, roughly $97 billion.
The summer push took the dollar from close to 164 yen, its strongest level in about 39 years, down to around 158.20. That is a move of about 3.5%. It was real, and it was fast.
Now look at where things stand. On November 20 the dollar bought about 158.55 yen, and Trading Economics data shows the yen still about 1.4% weaker than a year earlier. More than ¥27 trillion spent, and the yen has gone nowhere over twelve months. That is the clearest evidence that intervention treats the symptom while the rate gap keeps feeding the cause.
The Carry Trade Math Behind Every Yen Selloff
The rate gap turns into selling pressure through a trade called the carry trade. A fund borrows in yen, where money is cheap, converts it to dollars, and buys higher-yielding US bonds. It pockets the difference.
A worked example with real numbers
Say a fund borrows ¥160 million at a cost close to Japan's 2-year yield of 1.82%. At 160 yen per dollar, that converts to $1 million. The fund buys 2-year Treasuries yielding about 4.83%.
- Yearly income: $1 million x 4.83% = $48,300.
- Yearly borrowing cost: ¥160 million x 1.82% = ¥2.91 million, about $18,200.
- Net carry: about $30,100 a year, or 3% on the position.
Now the yen strengthens 3%, from 160 to about 155. The fund still owes ¥160 million. Buying that back now takes about $1,032,000 instead of $1,000,000. A 3% yen move erases the whole year's profit. The summer intervention moved the yen more than that in a few days.
This is why verbal warnings work at all. Every carry trader knows the asymmetry: small steady gains, sudden large losses. When Mimura says "too rapid," some of them close out, and closing out means buying yen. The warning partly does the ministry's job for free.
What Could Finally Turn the Yen
Intervention can cap the dollar. It cannot reverse the trend on its own. Three things could:
- A faster Bank of Japan. In a Reuters poll cited by investingLive, 86% of economists expected a December hike to 1.50%, and nearly 60% saw 1.75% by the end of March. Japan's October inflation came in at 2.3%, above the 2% target. A hike plus a signal of more would narrow the gap.
- A Fed that stops hiking. If US inflation cools and the Fed pauses, Treasury yields would likely fall and the dollar's yield edge would shrink from the other side.
- A risk-off scramble. When global stocks sell off hard, carry trades unwind at once and the yen tends to rally. Japan's 10-year yield fell for four straight days into November 20 as an AI-driven stock selloff pushed money toward bonds, Trading Economics reported.
Notice what is missing from that list: more intervention. The ministry has already shown it will spend tens of billions of dollars in a day. The next round would likely push the yen back toward the high 150s, as the last one did, and then the yield gap would go back to work.
What a Yen Move Means for Your Money
The effect on you depends on what you hold.
If you own an unhedged Japan stock fund in dollars, a stronger yen helps you, because each yen of company value converts into more dollars. A sudden 3% yen jump adds about 3% to your return even if Japanese shares do nothing. A hedged fund strips that out on purpose.
If you are travelling to Japan, 160 is a near four-decade high for the dollar, and your money stretches further than it has in years. Run the numbers on your budget with our currency converter. If intervention hits mid-trip, a 3% swing on a $3,000 budget is about $90.
If you own US stocks, watch the yen as a stress gauge. A fast yen rally often means carry trades are being forced shut, which can drain money from global stocks at the same time. Our explainer on what a strong dollar means for trips and funds covers the other side of this trade, and our guide to how bond yields signal what is coming shows why the yield gap leads the currency.
Frequently Asked Questions
Why is the Japanese yen so weak right now?
Mostly because of the interest rate gap. US Treasury yields were about 2.3 to 3 percentage points above Japanese government bond yields in late November. Investors earn more holding dollars, so money keeps flowing out of yen even after two Bank of Japan rate hikes this year.
At what level does Japan intervene in the yen?
Officials have never named one. They talk about speed and one-sided moves instead. In practice, both interventions this year came after the dollar rose above 160 yen, so traders treat that zone as the danger line.
How much has Japan spent on yen intervention?
Ministry of Finance data shows ¥11.73 trillion between April 28 and May 27, and about ¥15.4 trillion across July 30, July 31 and August 3. That is more than ¥27 trillion in total, with a record ¥7.98 trillion on July 30 alone.
Does currency intervention work?
It works for days or weeks, not for a trend. The summer operation pushed the dollar from near 164 to about 158.20 yen. Four months later the dollar was back near 160, because the yield gap that drives the trend had not changed.
Is a weak yen good or bad for Japan?
Both. Exporters earn more yen from overseas sales, and October exports hit a record. But imported food and energy cost more, which feeds the inflation now running above the Bank of Japan's 2% target and squeezes household budgets.
The Line Holds Until the Rates Move
The 160 line is real, but it is a line drawn in reserves, not in fundamentals. Tokyo has proven it will spend record sums, and now with US help, to stop a disorderly slide. It has not shown it can change the direction of travel.
Watch two dates instead of the exchange rate. The Bank of Japan's December meeting tells you whether the gap narrows from Tokyo's side. The Fed's December decision tells you whether it widens from Washington's. If the BOJ hikes and the Fed pauses, the yen has a real reason to rise. If not, expect another test of 160, another round of warnings, and possibly another record day.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult with a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.
Written by
Marcus Vance
Business & Money
Writes on business and personal finance for Quick Trend Insights, translating markets, rates, and company strategy into what it costs or saves a household.
Related Articles
View all
Nvidia SEC Probe: What It Means for Your Index Fund
The Nvidia SEC probe dragged down the AI trade. Here is what an accounting investigation does and does not mean, and the real math for index-fund investors.
FII Buying Explained: Why Sensex and Nifty Hit Highs
Record FII buying pushed Sensex and Nifty to nine-month highs as global markets fell. Here is how foreign flows move Indian stocks and what it means for SIPs.
Oil Price Drop: Why Brent Fell 32% From Its Peak
Oil price drop explained: Brent fell 32% from its October peak as the war risk premium faded and barrels returned. What it means for pump prices and investors.