
Strong Dollar: What It Means for Your Trips and Funds
The strong dollar buys 3.4% more yen than a year ago but fewer pounds. See what it means for your travel budget, international funds and money sent abroad.
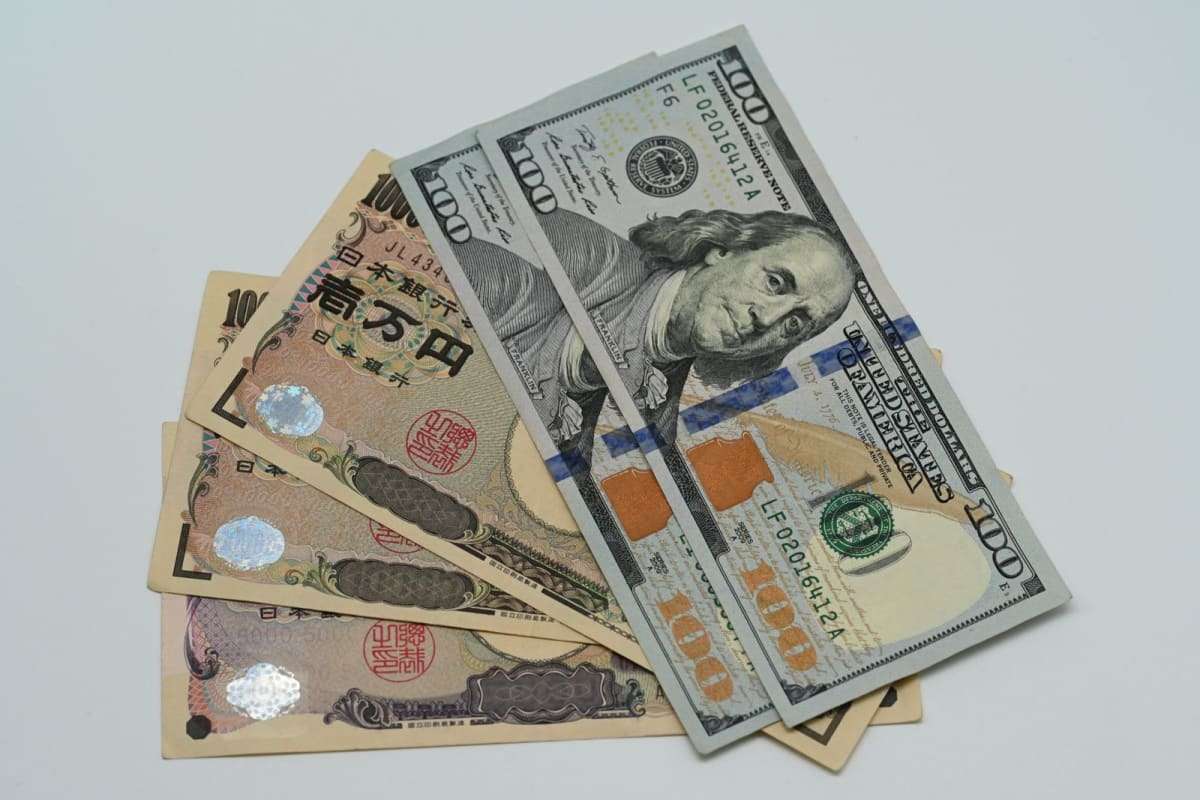
Table of contents
You booked a week in Tokyo for the spring and set aside $3,000 for spending money. A year ago that cash would have bought about ¥459,000. Change it this week and you get roughly ¥475,000, an extra ¥15,500 for nothing more than waiting. That is the strong dollar at work, and it touches far more than vacation budgets.
The same move that pads your trip can quietly shave returns off an international fund in your 401(k). It changes what a family member in India receives when you send money home. It even shifts the price of imported goods months from now. And the headlines calling this a "19-month high" only tell part of the story, because the dollar has climbed hard against some currencies and slipped against others.
This guide walks through what is driving the dollar right now, which currencies it is actually beating, and the simple math for your travel, investments and transfers.
Why the Strong Dollar Came Back This Month
Currencies move toward the highest safe return. When investors expect US interest rates to rise faster than rates elsewhere, they buy dollars to hold Treasury bonds and bank deposits that pay more. Rate expectations, not the economy's mood, are doing most of the lifting.
The trigger this month was inflation. The Bureau of Labor Statistics CPI release on November 10 showed consumer prices up 0.4% in October after a 0.6% jump in September. Core prices, which strip out food and energy, rose 0.3%. Those are hot numbers for a central bank that has already been hiking.
Traders reacted fast. By November 12, CME FedWatch data showed roughly a 91% chance of a quarter-point hike in December, up from about 67% a week earlier, according to FXStreet's market analysis. If you want the background on what the last increase did to borrowing costs, our breakdown of what the Fed's rate hike means for your wallet covers loans, cards and savings.
The rate gap with Japan
Japan shows the mechanism most clearly. The Bank of Japan has been far more cautious about raising its interest rate. On November 12, Bank of Japan board member Toichiro Asada said further hikes would tighten financial conditions and hurt growth. When one country signals higher rates and another signals restraint, money flows toward the higher yield, and the exchange rate follows.
Which Currencies the Dollar Is Beating, and Which It Isn't
"The dollar is strong" sounds like one fact. It is really a set of separate exchange rates moving at different speeds. The Federal Reserve publishes the official daily rates in its H.10 foreign exchange release, and comparing the first week of November with the same week a year earlier gives a clear picture.
- Japanese yen: 158.23 per dollar on November 6, against 152.97 a year earlier. The dollar buys about 3.4% more yen.
- Indian rupee: 93.91 per dollar, against 88.65 a year earlier. That is a gain of about 5.9% for the dollar, the biggest move of the four.
- Euro: $1.1154 per euro, against $1.1539 a year earlier. The euro now costs about 3.3% less.
- British pound: $1.3371 per pound, against $1.3107 a year earlier. Here the dollar actually lost ground, so a pound costs you about 2% more.
Now zoom out. The Fed's nominal broad dollar index, which weights the dollar against the currencies of major US trading partners, read 121.88 on November 6. A year earlier it was 121.69. On a trade-weighted basis, the dollar is roughly where it was twelve months ago.
What changed is the path. The index fell to 117.44 on January 29, then climbed about 3.8% to its current level. It still sits about 6% below its January 2025 high of 130.04. So the "multi-month high" headlines are accurate, but they describe a recovery from a slump, not a dollar at record strength.
The yen's summer scare
The yen story has a recent twist. H.10 data shows the dollar reached 163.86 yen on July 29, and Reuters reports Japan spent a record ¥15.4 trillion defending its currency in a series of interventions between July 30 and August 3, one of them carried out jointly with the United States. On November 12, with the dollar back near 160 yen, Japan's top currency diplomat, Atsushi Mimura, told reporters: "It's still too early to forget what happened this summer."
That matters for your planning. A level near 160 yen is where Tokyo has stepped in before, and an intervention can move the rate several yen in a day. If you are waiting for an even better rate before a trip to Japan, you are betting against a government that has shown it will act.
What a Strong Dollar Means for Your Travel Budget
Travel is where most people feel exchange rates directly. Here is the math on a Japan trip, using the Fed's published rates.
Worked example: a week in Japan
- Spending money: $3,000. At 153.06 yen (November 7 last year), that converts to ¥459,180. At 158.23 yen, it converts to ¥474,690. You gain ¥15,510, worth about $98 at today's rate.
- A hotel at ¥30,000 a night: that cost about $196 a night at last year's rate and about $190 now. Over seven nights, the bill drops from roughly $1,372 to $1,327.
- At the July peak of 163.86 yen, the same $3,000 would have fetched ¥491,580. Timing still matters, but nobody rang a bell at the top.
Europe is a smaller win of about 3% on the euro. Britain runs the other way. A London trip with a £2,000 budget costs about $2,674 at this week's rate, compared with $2,621 a year ago. Check the specific currency, not the headline.
To run your own numbers, plug your budget into our currency converter before you decide when to change money. Two habits help more than timing the market: pay in the local currency when a card terminal offers a choice (dynamic currency conversion adds a markup), and use a card with no foreign transaction fee.
How a Strong Dollar Hits Your International Funds
Here is the side of the coin that rarely makes the travel pages. When you own foreign stocks through a fund, you earn two returns: the change in the stock price in its home currency, and the change in that currency against the dollar. When the dollar rises, the second return turns negative.
Take $10,000 in a eurozone stock fund held over the past year. Suppose the stocks rose 5% in euro terms. The euro fell from $1.1539 to $1.1154, a drop of about 3.3%. Your dollar result is 1.05 multiplied by 0.967, or about 1.5%. The portfolio ends near $10,150 instead of $10,500.
The same drag hits funds holding Japanese or Indian stocks, and it hit harder in India, where the rupee fell almost 6%. A pound-denominated holding did the reverse and got a small currency tailwind.
Should you hedge or sell?
For most long-term investors, no. Currency swings tend to wash out over long holding periods, while the reason to own foreign stocks stays the same: they spread your risk beyond US companies. If you are unsure how much overseas exposure you really have, our look at why your index fund is not as diversified as you think shows how concentrated a plain US index fund has become.
Currency-hedged funds exist and do remove most of this effect, at the cost of a slightly higher expense ratio and giving up the gains when the dollar falls. Switching into one after the dollar has already rallied means paying for protection after the damage is done.
Who Wins and Who Pays at Home
A stronger dollar spreads its effects unevenly across households. A quick scorecard:
- Sending money abroad: A $1,000 transfer to India now delivers about ₹93,910, against ₹88,650 a year ago. That is ₹5,260 more for the same dollars.
- Imported goods: Importers pay less in dollars for goods priced in yen or euros. That relief reaches store shelves slowly, often over several months, and tariffs can absorb it before it reaches you.
- US exporters and multinationals: Their foreign sales are worth fewer dollars when converted back. That can weigh on earnings, which matters if you hold large US company stocks.
- Workers in export industries: Pricier American goods abroad mean slower orders for factories and farms that sell overseas.
For inflation, a stronger dollar is a mild help. Cheaper imports pull against the price pressure the Fed is fighting. That is one reason central banks watch the exchange rate closely, even though they rarely say they target it.
Frequently Asked Questions
Is a strong dollar good or bad for the US economy?
Both. It makes imports and foreign travel cheaper and helps slow inflation, but it makes US exports more expensive abroad and reduces the dollar value of foreign profits for US companies. Whether it helps you depends on whether you mostly buy from abroad or sell to it.
Why is the dollar getting stronger right now?
Mainly because markets expect the Fed to keep raising rates after a hot October inflation report, while central banks such as the Bank of Japan sound more cautious. Higher expected US rates draw investment money into dollars.
Is now a good time to exchange dollars for yen?
The dollar buys close to 160 yen, near the level where Japan intervened over the summer. Rates can fall several yen quickly if Tokyo steps in again, so changing part of your travel money now and the rest later spreads the risk.
Does a strong dollar hurt my 401(k)?
Only the international part. Foreign stock funds lose some return when their home currencies fall against the dollar. US stock funds are affected indirectly, through lower overseas earnings at large multinationals.
Where can I check the official dollar exchange rate?
The Federal Reserve publishes daily noon buying rates for major currencies, plus a broad trade-weighted dollar index, in its weekly H.10 release. Banks and card networks add their own spread on top of those rates.
The Bottom Line
The strong dollar you are reading about is real but selective. It buys about 3.4% more yen and nearly 6% more rupees than a year ago, slightly fewer pounds, and on a trade-weighted basis it has only climbed back to where it stood last November. The fuel is the expectation of higher US rates, so the next Fed meeting and the next inflation report will decide whether it lasts.
Use it where it helps: lock in part of your travel money, send transfers while the rate favors you, and leave your international funds alone. The dollar's direction can flip on one inflation print. Your plan should not depend on guessing which way.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Always consult with a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.
Written by
Marcus Vance
Business & Money
Writes on business and personal finance for Quick Trend Insights, translating markets, rates, and company strategy into what it costs or saves a household.
Related Articles
View all
Trade Deficit: Why AI Servers Now Drive US Imports
The US trade deficit hit $105 billion in September, and imported AI servers now drive most of it. See why that cancels out in GDP and what it means for you.
Credit Card Debt Jumped: What the Fed Data Means for You
Credit card debt grew at a 14.5% annual pace in September, but Fed data tells a calmer story. See what it means and what a $6,000 balance costs at 22% APR.
Annual Inflation Rate Missing From CPI: How to Estimate It
The annual inflation rate is missing from the October CPI report. Here's the BLS method to estimate it (near 4%) and what it means for rent, raises and the Fed.